

Quick Answer
Yes, you can buy a Rolex on finance. Most authorised retailers work with third-party lenders to offer monthly payment plans, typically spread over 12 to 36 months.
Before you apply, understand five key elements: the deposit, the monthly payment, the APR (annual percentage rate), the term length, and the total amount payable once interest is included. These decide whether the arrangement fits comfortably within your budget.
The question comes up more often than you'd expect. Someone's been considering a particular watch for months. They know exactly which model they want, they've done the research, and they're ready to move forward. Then they pause and ask if they can spread the cost.
What we've noticed over the years is that people often assume Rolex finance is either unavailable for luxury items or somehow problematic. Neither is true. Finance arrangements vary widely, and understanding how they work protects both the purchase and your relationship with the watch over time.
When someone asks us "can you buy a Rolex on finance?", the answer is straightforward: finance is available. What matters more is whether it's the right choice for you, and whether you've understood the commitment before signing.
This guide is general information, not financial advice.
Rolex Finance UK: Pay Monthly, 0% Finance and Interest-Free Explained
Buyers describe Rolex finance in many ways, but they're mostly asking about the same few options:
|
If you search for |
What it usually means |
|---|---|
|
Rolex finance, finance on Rolex, finance for Rolex watches, financing Rolex watches |
Spreading the cost of a Rolex through a credit agreement with a lender |
|
Buy a Rolex on finance, finance a Rolex, Rolex watch on finance, Rolex watches on finance |
Paying a deposit and repaying the rest in monthly instalments |
|
Rolex pay monthly, pay monthly Rolex, Rolex watch pay monthly, Rolex watches monthly payment |
The monthly instalment structure of a finance plan |
|
Rolex 0 finance, Rolex 0 financing, 0 finance Rolex UK, Rolex watches on 0 finance, Rolex watches UK 0 finance |
0% APR credit, usually over shorter terms, subject to status |
|
Interest free Rolex, interest free on Rolex watches, Rolex interest free |
The same 0% APR option: no interest if you clear the balance within the term |
|
Rolex finance UK, finance Rolex UK, Rolex UK finance, Rolex watch finance UK |
Finance arranged by a UK retailer or credit broker, regulated in the UK |
|
Pre-owned Rolex finance, Rolex finance no deposit |
Finance on second-hand watches, and whether a deposit is needed (see below) |
The sections below cover each in detail, so you can finance Rolex watches knowing exactly what you're agreeing to.
What Does Finance on Rolex Watches Mean?
Finance lets you spread the cost of a Rolex over time instead of paying the full price upfront.
- A formal credit agreement: it isn't a casual payment split. Finance on Rolex watches is usually arranged through the retailer in partnership with a finance provider.
- Who lends: the retailer doesn't lend you the money. A third-party lender assesses your application and, if approved, pays the retailer in full. You then repay the lender over the agreed term.
- How it's structured: you pay a deposit and spread the balance across an agreed term. Each monthly payment covers the principal and the interest that has accrued.
- Interest: because of interest, the total you repay is higher than the watch's price. That's the cost of having the watch now rather than waiting to save.
In short: finance lets you own the watch today whilst paying over time, but interest means you'll pay more than the sticker price unless the term is interest-free.
Does Rolex Offer Financing Directly?
No. Rolex doesn't offer financing directly to buyers. You access it through retailers, credit brokers or finance providers that work independently from the brand.
- Authorised retailers: most partner with third-party lenders. The retailer facilitates the arrangement, but the credit comes from a separate finance company.
- Credit brokers: some retailers work with brokers who connect you with suitable lenders based on your circumstances.
- At The Diamond Box: we arrange Rolex finance as a credit broker, not a lender. We work with a panel of lenders to find terms that suit your situation, introduce you to finance providers and support you through the application, but we don't provide the credit ourselves.
- Where responsibility sits: the lending relationship is between you and the finance company. They assess your application, set the terms and manage the repayment schedule.
How Rolex Finance Works in the UK
The process follows a clear sequence, though exact steps vary slightly by retailer and lender.
- Choose your Rolex. You'll know the model, specification and price. This isn't the point to be uncertain about which watch you're committing to.
- Review the finance options. Check the repayment term, APR, deposit and total payable, which decide whether the arrangement works within your budget once interest is included.
- Complete the application. You provide personal and financial information so the lender can assess your creditworthiness. It usually takes a few minutes, online or in person.
- Wait for a decision. Most lenders give an initial decision quickly, often within minutes.
- Read the credit agreement. If accepted, you'll receive the full agreement with the monthly payment, interest rate and total repayable. Read it carefully before signing.
- Pay the deposit and complete. Once you've signed and paid the deposit, the purchase completes and the watch is yours.
If your application is declined, or the terms don't suit you, you're under no obligation to proceed. You can reconsider, wait or explore alternatives.
Monthly Payments on Rolex: Deposit, Term Length and Total Cost
Three elements shape what you pay: the deposit, the length of the repayment term, and the total cost once interest is included.
- Deposit (typically 10-30%): a higher deposit means less to borrow, a lower monthly payment and less interest overall. A lower deposit keeps more cash with you now but raises both the monthly cost and the total.
- Term length: spreading repayments over 36 months instead of 12 lowers each Rolex monthly payment, but you pay interest for longer, so the total cost rises.
- Judge the whole cost: monthly payments make the purchase feel more manageable, but always weigh them against the full Rolex cost, not only the monthly figure.
Example: Rolex Monthly Payments on a £10,000 Watch
|
Term |
Monthly payment |
Total payable |
Interest paid |
|---|---|---|---|
|
12 months at 0% APR |
£833 |
£10,000 |
£0 |
|
12 months at 9.9% APR |
£879 |
£10,544 |
£544 |
|
24 months at 9.9% APR |
£461 |
£11,064 |
£1,064 |
|
36 months at 9.9% APR |
£322 |
£11,599 |
£1,599 |
Illustrative only: no deposit, and a 9.9% APR example. Actual rates, terms and approval depend on the lender, your credit profile and the watch. Credit is subject to status and affordability.
- What the example shows: a £10,000 watch over 36 months costs about £322 a month, which feels accessible, but the total repayable is closer to £11,600. That extra £1,600 is the cost of spreading the payments.
- If the total feels disproportionate: a shorter term or a larger deposit might serve you better.
|
Factor |
What it means |
|---|---|
|
Watch price |
Full listed price of the Rolex |
|
Deposit |
Amount paid upfront |
|
Loan amount |
The amount being financed |
|
Term length |
How long payments run |
|
APR |
Whether the plan is 0% or interest-bearing |
|
Total payable |
Final amount paid after all monthly payments |
Rolex Finance With No Deposit
Buyers often ask whether you can finance a Rolex with no deposit.
- It depends: deposit requirements vary by lender, watch and your status.
- Part-exchange can be the deposit: the trade-in value of a watch you own can cover it.
- Ask before you apply: check what the lender requires for the watch you want.
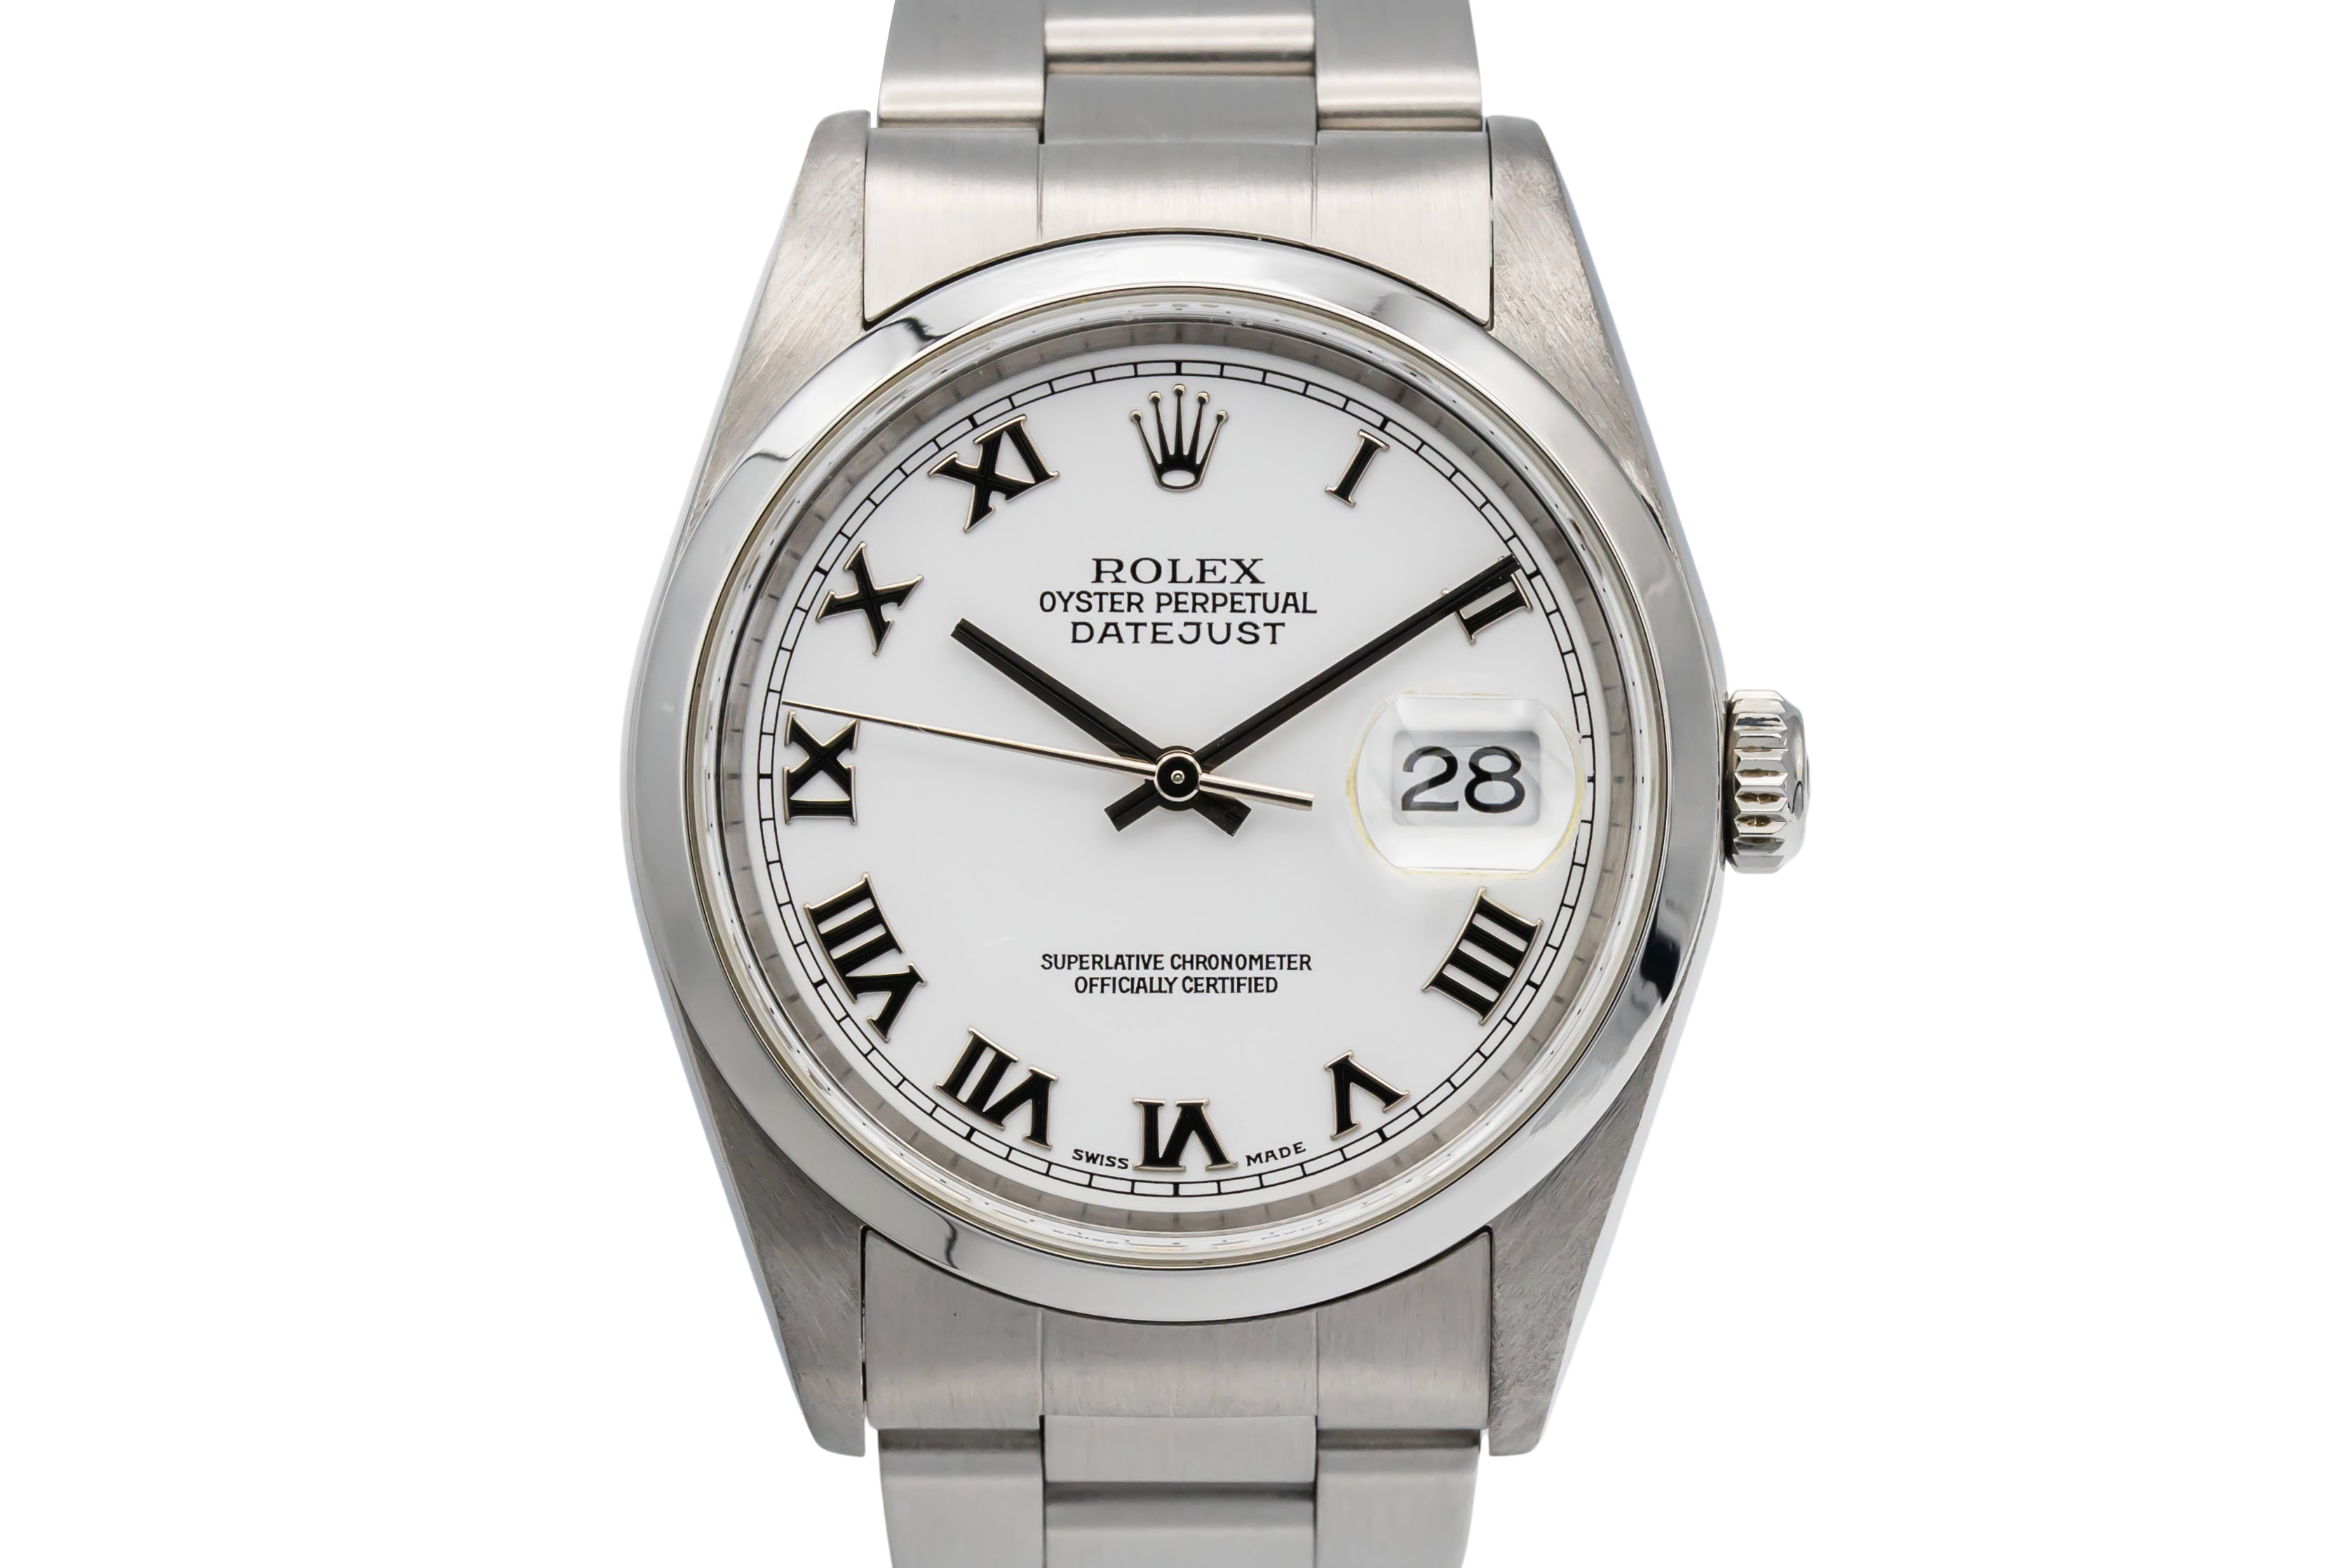 Rolex DateJust 36mm Stainless Steel Oyster 16200 2001
£4,495.00
Available
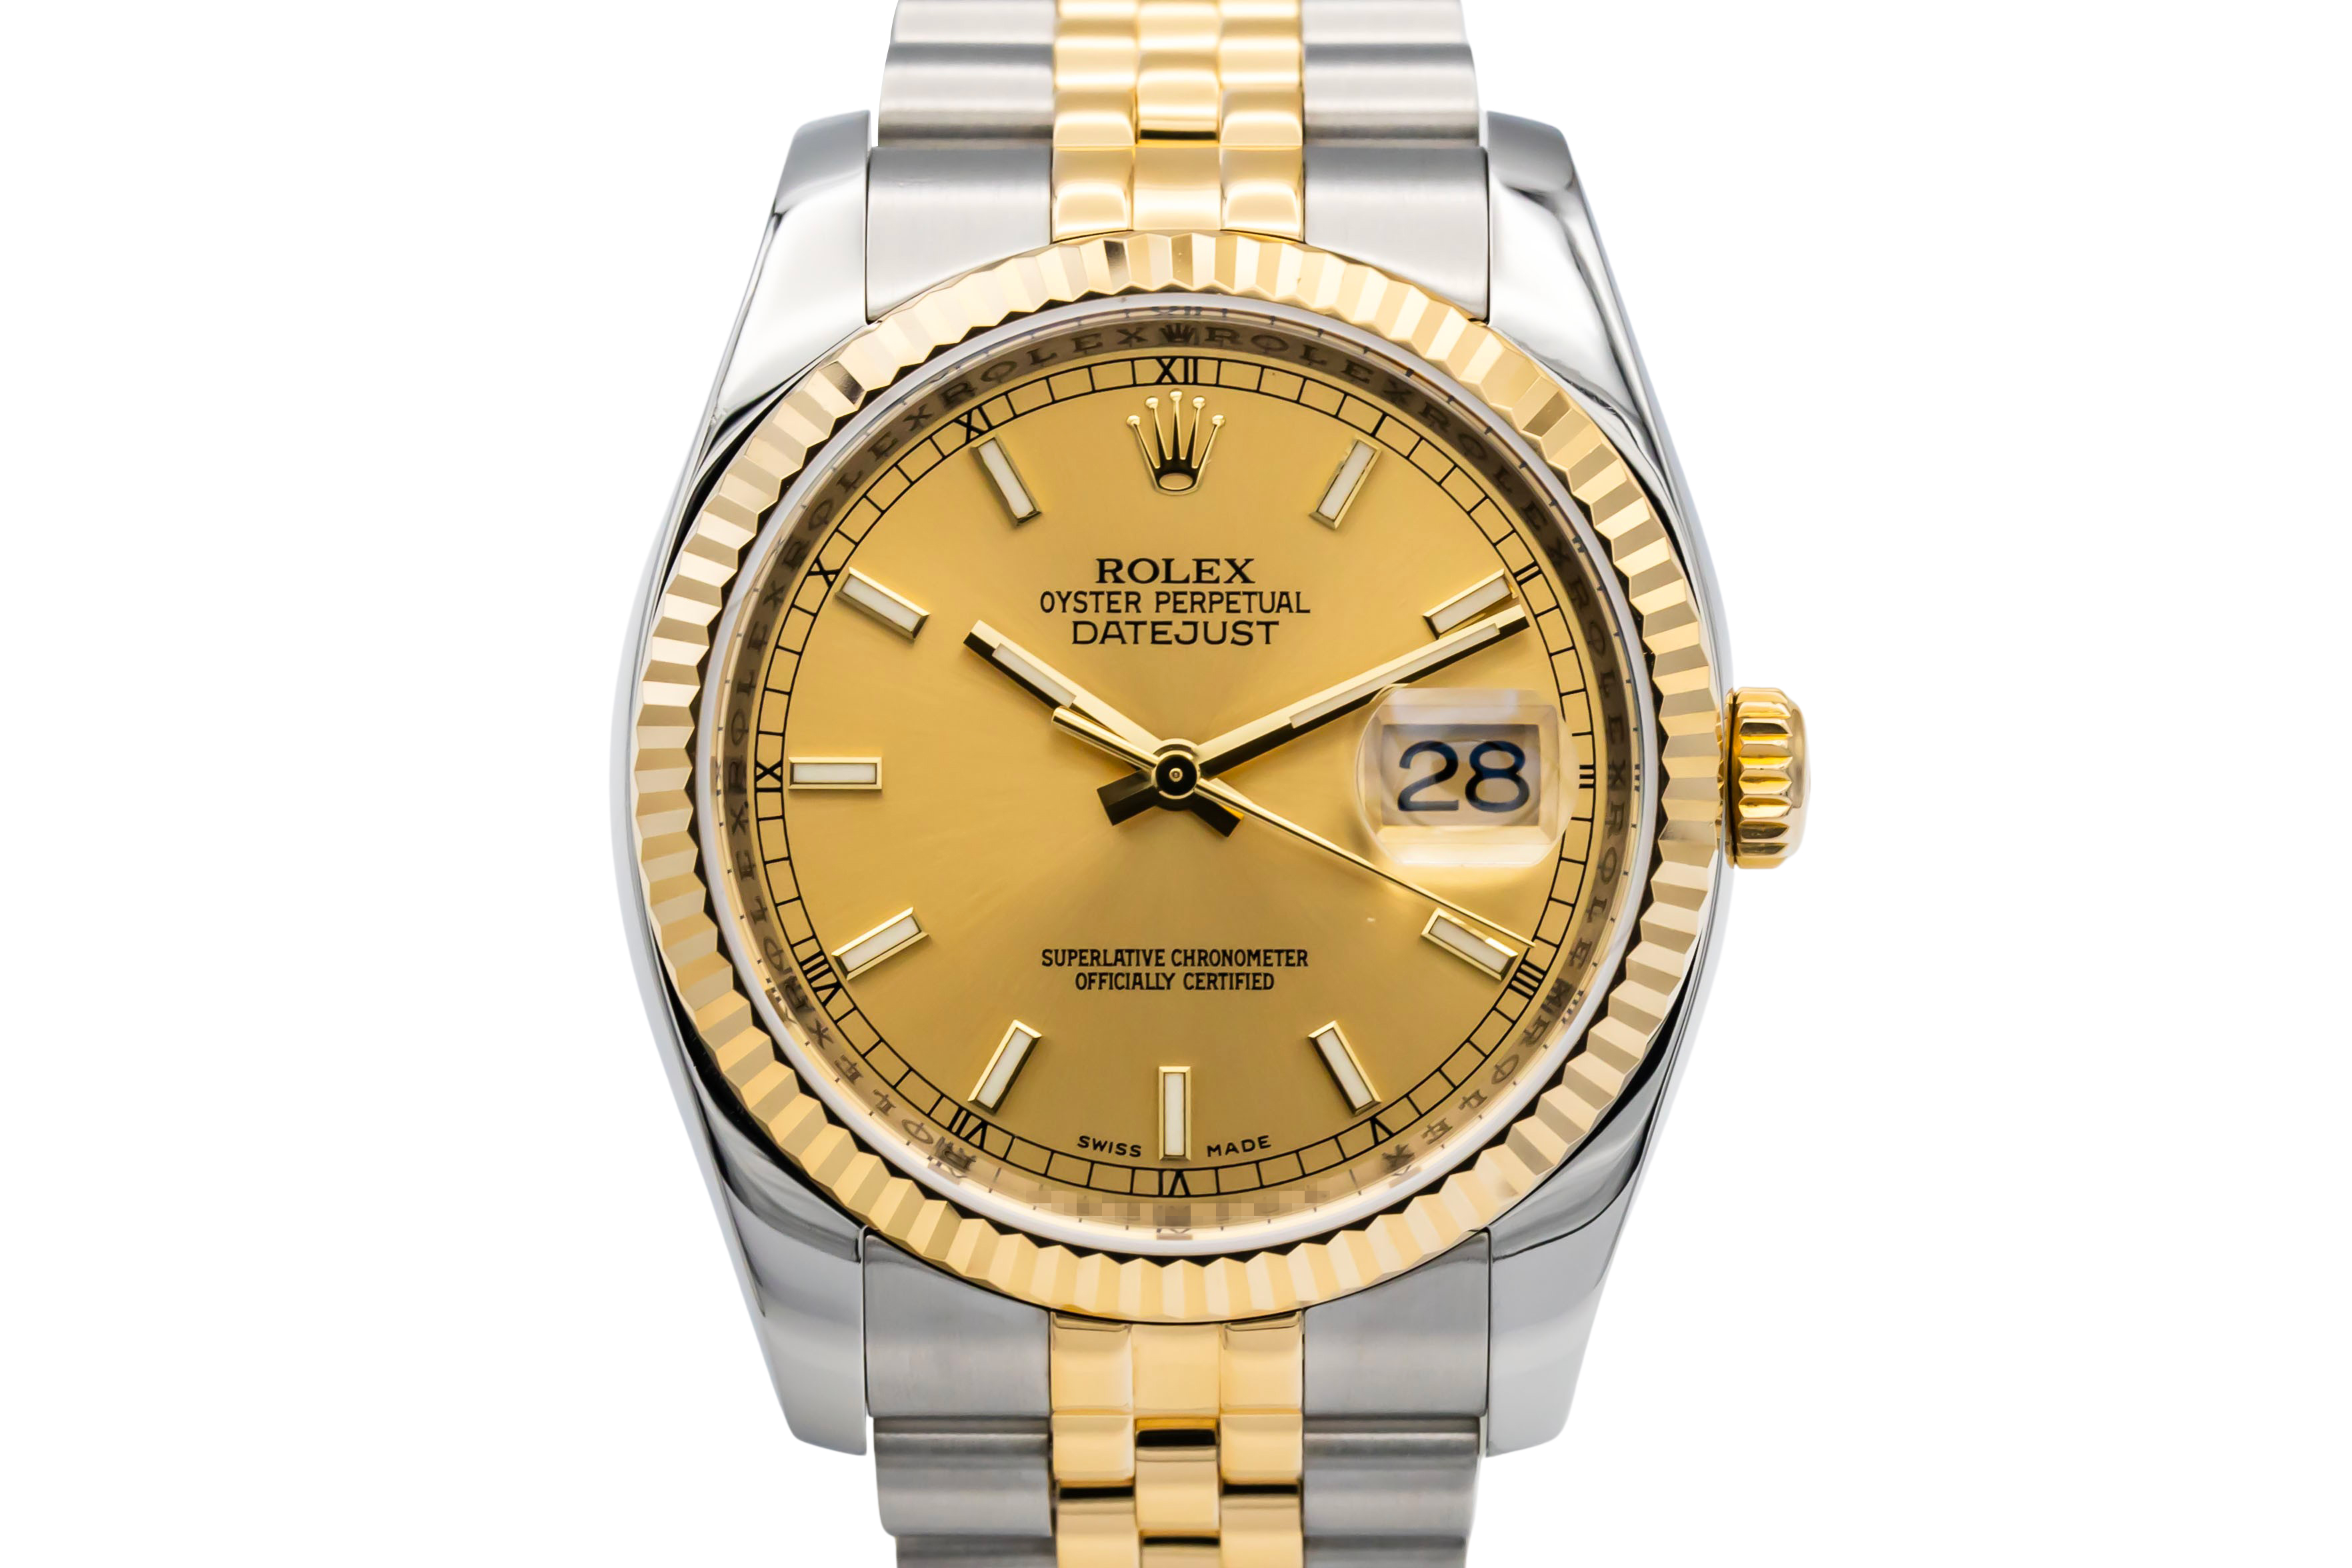 Rolex DateJust 36mm Steel & 18ct Yellow Gold Jubilee 116233 2008
£8,995.00
Available
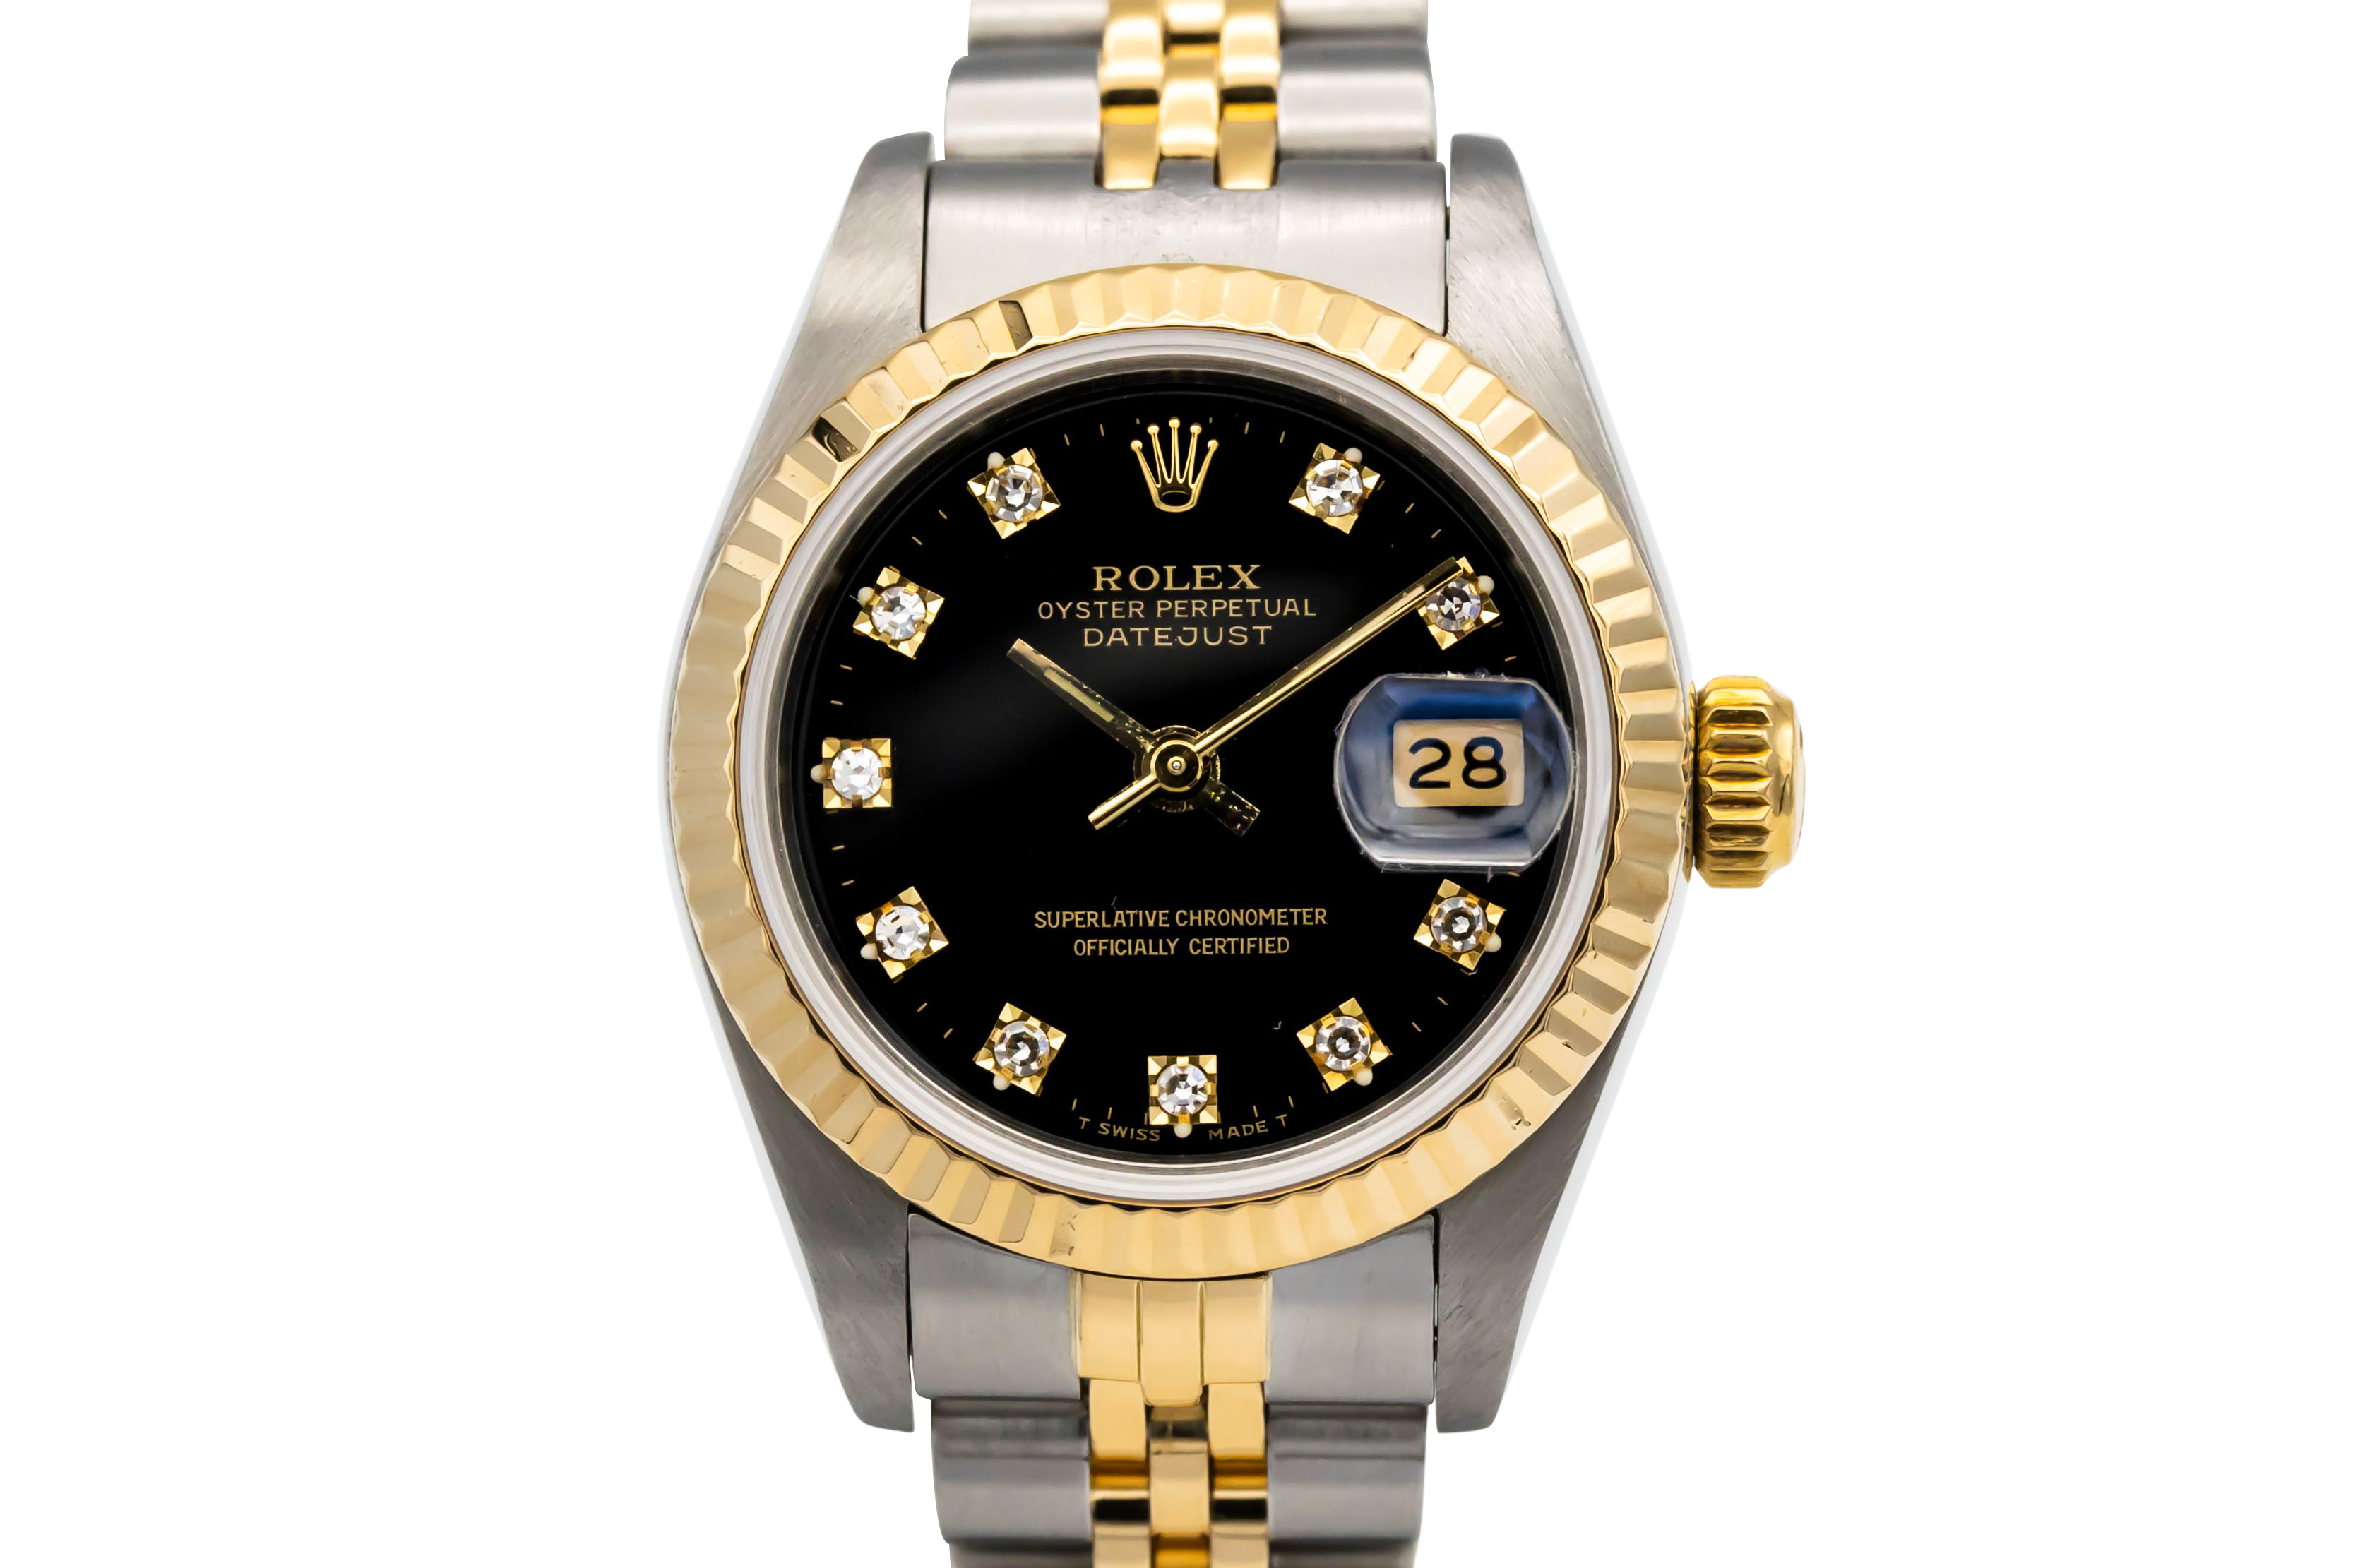 Rolex Lady DateJust 26mm Steel & 18ct Yellow Gold 69173 1985
£4,995.00
Available
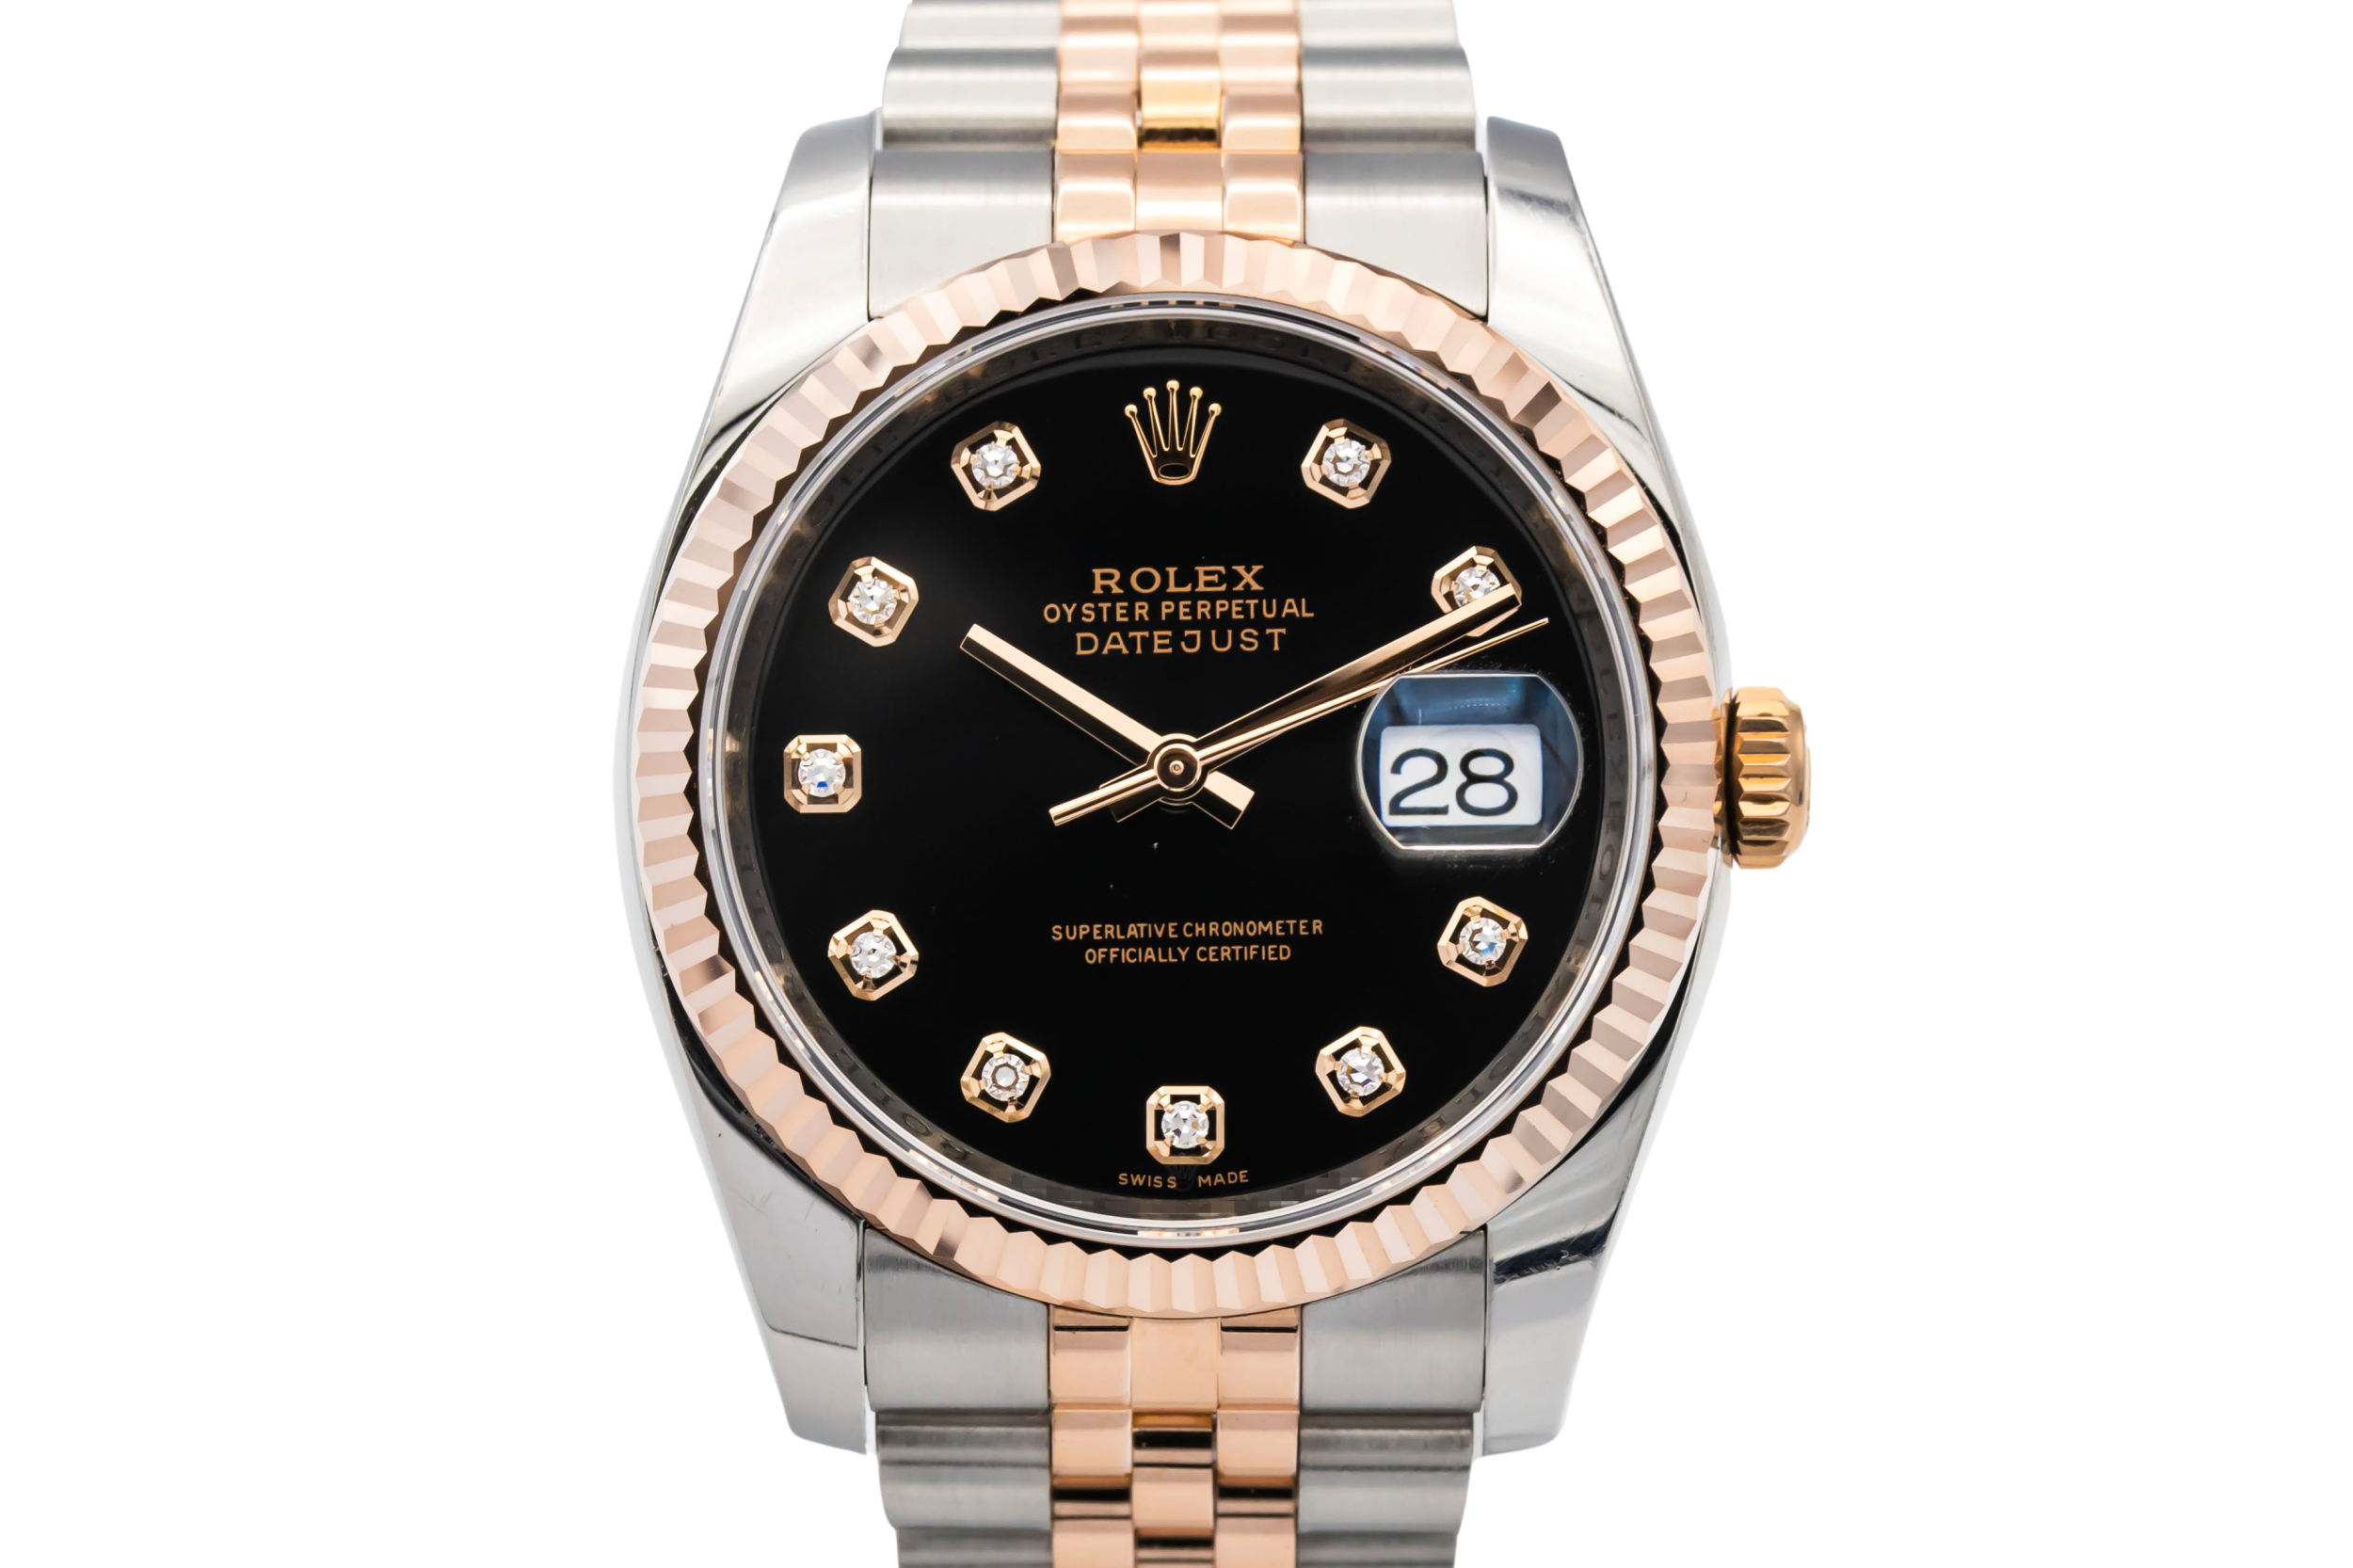 Rolex DateJust 36mm Stainless Steel 18ct Rose Gold Jubilee 116231 2016
£9,950.00
Available
Rolex Interest Free Finance: What 0% APR Really Means
Rolex interest free finance sounds simple: you borrow, repay over time, and no interest is added. In principle, that's correct, but conditions apply.
- What 0% APR means: you won't pay interest during the eligible term, provided you meet the plan's requirements and are approved on those terms. Clear a 12-month 0% plan within the term and you repay exactly what you borrowed.
- Not everyone qualifies: your credit profile plays a role. With limited credit history or a score below the lender's threshold, you may be approved but at a standard interest rate. The 0% offer is conditional, not guaranteed.
- Time-limited: if you don't clear the balance by the end of the term, interest typically applies to what remains. Some agreements apply interest retrospectively, charging it on the full original balance as if the 0% period never existed. Terms vary, so read the agreement carefully.
- Availability changes: it depends on the watch's value, your deposit and the lender's current promotions. When financing Rolex watches in the UK, what's available today might not be offered next month.
- When it works well: you're confident you'll clear the balance within the term and your credit profile qualifies. If either feels uncertain, factor in the possibility of paying interest.
Rolex on Finance 0% APR: When It May Be Available
Rolex on finance 0% APR isn't offered everywhere or at all times. Availability depends on the retailer, their lender, and the terms promoted when you apply.
- At The Diamond Box: we offer Rolex 0 finance, meaning 0% APR interest-free credit, over shorter terms, typically 6 to 12 months, provided you clear the balance in the agreed period. For longer plans, we offer competitive interest rates that reflect the extended repayment window.
- Criteria vary: some retailers need a higher deposit for interest-free finance, and others restrict 0% finance on Rolex watches to certain models or price brackets. A reputable Rolex dealer in London will be transparent about the terms before you commit.
- Promotions: a retailer might offer Rolex 0 finance during specific months or on selected stock, so ask whether it's available for your watch and whether the offer has a time limit.
Can You Finance a Pre-Owned or Vintage Rolex?
Yes. Finance isn't restricted to new watches, and pre-owned Rolex finance is widely available, including for vintage models.
- At The Diamond Box: finance is available on new, pre-owned and vintage Rolex watches listed on the website. You're not limited to the current catalogue if you want a discontinued reference or a vintage model with character.
- What may change: the watch's age or condition doesn't typically affect whether finance is available, though the lender may adjust the deposit or rate depending on the watch's value and your credit profile.
- Check before choosing a plan: if you're weighing up a pre-owned Rolex, review the condition, reference number, paperwork, service history and warranty. Financing a watch you haven't fully researched or inspected feels more pressured than it needs to be.
- Value: pre-owned and vintage watches often offer better value than new, especially for models no longer in production or where the secondary market price sits below retail. Finance makes these accessible without the full amount upfront.
- Condition varies: ask about service history, authenticity verification and any restoration work. A reputable dealer will be transparent about these.
Which Rolex Models Make Sense to Buy on Finance?
Which model to finance depends less on the watch and more on why you're buying it and how you'll wear it. Some models come up more often simply because they're the ones people search for.
- Submariner: one of the most requested references; versatile and recognisable, daily or occasional.
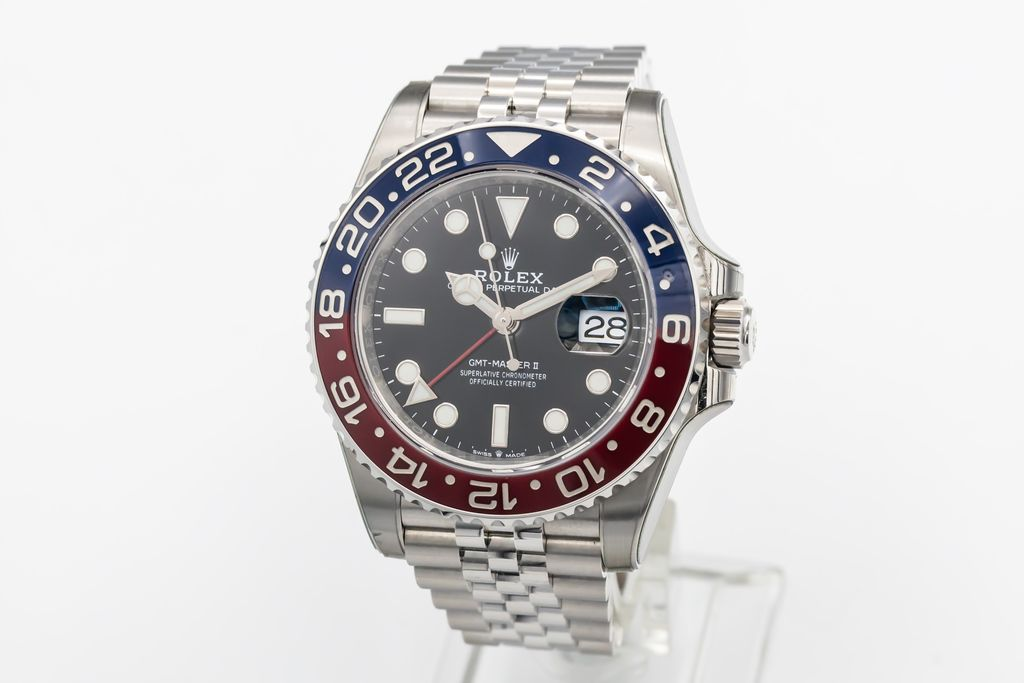
- GMT-Master II: combines function with a distinctive look that has become increasingly sought-after.
- Daytona: among the most desirable, though availability is limited and prices reflect demand. Financing one makes sense if you've found one and the numbers work, but be realistic about the secondary market if your circumstances change.
- Datejust: a different price point, with more variety in dial colours, bezel styles and sizes, and often easier to source than sports models.
- Yacht-Master and Day-Date: each attracts its own interest, with its own character within the collection.
- Supply: the Rolex waiting list affects access to popular models. Some references are available immediately pre-owned whilst new ones take months or years, and where a model is hard to find, a dealer can often source a watch for you. Finance works for either route.
Finance vs Personal Loan vs Part-Exchange
There are three main ways to fund a Rolex purchase.
|
Option |
Best for |
Risk |
|---|---|---|
|
Retailer finance |
Buyers who want structured monthly payments and a convenient process |
Approval depends on status |
|
Personal loan |
Buyers comparing bank rates and wanting more control over terms |
Slower, and not tied to the watch purchase |
|
Part-exchange + finance |
Buyers who already own a watch |
Valuation affects the deposit |
- Retailer-arranged finance: the most common route. Application happens at the point of sale, approval is usually quick, and the retailer or broker supports you. Rates depend on your credit profile and term.
- Personal loan: from your bank or building society. You're not tied to the retailer's lender and, with strong credit, may secure a better rate, but you'll need approval before committing to the purchase.
- Part-exchange: at The Diamond Box, the trade-in value of your existing watch is used as a deposit and the remaining balance is financed. That reduces what you borrow, lowering the monthly payment and total interest. It works well when upgrading within Rolex or moving from another brand, and feels more like reallocating what you own than taking on debt.
- Choosing: retailer finance if speed and convenience matter, a personal loan if you want more control over the rate and terms, part-exchange if you have a watch you no longer wear.
Is Buying a Rolex on Finance a Good Financial Decision?
Whether financing a Rolex makes sense depends on your circumstances and why you're buying. There's no single answer, but clear principles protect you from a decision you'll regret.
- Comfortable monthly payment: it shouldn't require cutting back elsewhere, depend on hoped-for income increases, or leave no room for unexpected costs. If it feels tight now, it'll feel tighter in six months.
- Don't rely on resale: some models hold value well, others less so. If your plan depends on selling later to recover your money, you're taking on risk that doesn't belong in a luxury purchase. Finance the watch because you want to wear it, not because you hope it appreciates.
- Check the terms: APR, total payable, term length and early repayment rules decide the true cost and your flexibility. A low monthly payment over a long term often hides a high total cost.
- A luxury purchase first: Rolex watches hold value better than many luxury goods, but they aren't financial instruments. If the total cost only makes sense because the watch might appreciate, you're approaching the decision from the wrong direction.
How to Apply for Rolex Finance at The Diamond Box
The steps are the ones set out in "How Rolex Finance Works in the UK" above. What's specific to The Diamond Box:
- Choose from any stock: a new model, a pre-owned piece or a vintage reference. You'll see the condition, specification and price before you commit.
- See the terms for that watch: the deposit, APR, term, monthly payment and total payable are shown together, so you can judge whether the total feels proportionate to the watch's value to you.
- Apply online or in our showroom: the application typically takes a few minutes.
- A decision within 48 hours: we aim for full approval within 48 hours of the lender reviewing your application.
- Subject to status: finance is subject to status and affordability checks, so approval isn't guaranteed. Lenders assess each application individually on credit history, income and existing commitments, and terms vary between applicants.
What to Consider Before Financing a Rolex
The availability of finance doesn't make it the right choice for everyone. Think these through before committing.
The Total Cost Increases
Even at modest rates, spreading payments over two or three years adds a meaningful amount, as the example above shows. It's worth comparing that interest with other uses for the money.
Your Credit Profile Matters
- Finance applications involve a credit check, and approval isn't guaranteed.
- Limited credit history or missed payments make a higher rate, or a decline, more likely.
- Several applications in a short period can temporarily lower your credit score.
Affordability Extends Beyond the Monthly Payment
Lenders assess affordability on your income and commitments. Consider your own flexibility too, because a payment that's comfortable now must still be comfortable if circumstances change.
Early Repayment Terms Vary
Some agreements let you settle early without penalty, whilst others charge a fee. If you might clear the loan early, clarify this before signing.
The Watch Is Yours, but the Debt Remains
You own the watch outright from the point of purchase, but the debt stays your responsibility whatever happens to it. If it's lost, stolen or damaged, you still owe the full amount unless insurance covers the outstanding balance.
When Rolex Finance Makes Sense
There's no universal rule. What works for one person feels uncomfortable for another, but patterns emerge.
Finance Works Well When
- You've found a specific watch unlikely to stay available. Availability fluctuates, and steel sports models in particular are hard to source. If the numbers work, finance bridges the gap.
- You're confident in your financial stability over the term. Steady income, predictable outgoings and a buffer for unexpected costs make payments easier to manage.
- The rate is low or the term is interest-free. If you'll clear it within the window, there's minimal downside.
Worth Reconsidering When
- You're financing because the full price feels uncomfortable. Finance doesn't change the value. It defers the payment, so ask whether it's the right purchase right now.
- You're uncertain about the watch. Finance should support a decision you've already made, not help you make it.
What Happens If Circumstances Change
Financial commitments that feel manageable at the outset can become difficult if circumstances shift.
- Don't ignore it: if you're struggling to meet repayments, contact your lender early. Lenders generally prefer to work with you, and many will consider payment holidays, term extensions or revised schedules.
- Selling to clear the debt: selling the watch is an option, but second-hand value is often below the outstanding balance, particularly in the early months when you've paid mostly interest. You'd need to cover any shortfall.
- Insurance matters: make sure your policy covers the full replacement value and, ideally, the outstanding finance balance in the event of loss or theft. Not all policies do this automatically.
Alternatives to Financing a Rolex
Finance isn't the only way to make a high-value purchase more accessible.
- Saving over time: the most straightforward option. It takes patience, but you own the watch outright from day one with no commitment. It suits models that aren't urgently scarce.
- Part exchange: we've worked with customers who've part-exchanged their way up over years, building value gradually without taking on debt.
- A secured loan: owners of valuables sometimes use a secured loan against them instead of a retail credit agreement.
- Smaller steps: start with a more accessible reference and upgrade later. Ownership is ownership, and your first piece doesn't have to be your last.
What We've Noticed Over the Years
The customers who feel best about their purchases, financed or otherwise, share certain patterns.
- They take their time: they've weighed the alternatives and planned for the full term.
- They're clear about why they're buying: it matters to them for reasons beyond the name or status, and it's a piece they'll wear, care for and keep, not something acquired on impulse.
When those things are in place, finance works well. When they're not, it tends to create problems that could have been avoided.
Conclusion
Financing a Rolex isn't inherently good or bad. It's a tool that works best when used thoughtfully. What matters isn't how you pay, but whether the watch is right for you, the commitment feels manageable, and you're deciding from clarity rather than pressure.
Thinking about Rolex finance? Visit us in North London or call 020 8838 3655 to talk through your options.
FAQs
Can you get a Rolex watch on finance in the UK?
Yes. You can put a Rolex watch on finance in the UK through authorised retailers and credit brokers working with regulated lenders. Rolex watches on finance are available new, pre-owned and vintage, subject to status and affordability, so you can finance Rolex watches without paying the full price upfront.
Can you buy a Rolex on finance with The Diamond Box?
Yes. We act as a credit broker, working with a panel of lenders to arrange finance on new, pre-owned and vintage Rolex watches, subject to status.
Does Rolex offer financing directly?
No. Finance comes from third-party lenders through authorised retailers or credit brokers.
Are monthly payments on Rolex watches available for pre-owned models?
Yes, including discontinued and vintage references.
Is Rolex interest free finance always 0% APR?
No. 0% APR is conditional on your credit profile and the term, as explained above.
Can I use part-exchange as a deposit for Rolex finance?
Yes. The trade-in value of your existing watch can be used as the deposit, with the remainder financed.
Can you finance a Rolex with no deposit?
It depends on the lender, the watch and your status. Ask what's required before you apply.
How much are monthly payments on a Rolex?
It depends on the price, deposit, term and APR. The example table above shows how a £10,000 watch changes across terms.
What happens if the Rolex costs more than the finance limit?
You'd cover the difference with a larger deposit or another funding route. Some buyers combine finance with part-exchange, and a personal loan can sometimes offer higher limits.
Will financing a Rolex affect my credit score?
Yes. The credit check leaves a mark on your file and can lower your score temporarily, whilst on-time repayments help build your history.
What happens if I miss a payment?
It can affect your credit score and trigger charges, so contact your lender early to discuss options.
Credit subject to status and affordability. Terms and conditions apply. Hallmark Marketing LTD T/A The Diamond Box is a credit broker and is authorised and regulated by the Financial Conduct Authority.